A project owner who approaches a bank with an optimistic forecast and three rough quotes often leaves without an answer. In 2026, bank analysts combine human review with algorithmic scoring to assess every financing application. Building a strong application starts with understanding this dual screening process and organizing every document to meet its requirements.
Algorithmic scoring and human review: what the bank looks at first
Before an advisor opens your application, an algorithm ranks it. Automated screening systems assess whether the amount requested is consistent with the applicant’s stated repayment capacity and financial history. A discrepancy between projected revenue and fixed costs can be enough to trigger an immediate rejection at this stage.
The advisor then reviews applications that pass this first screening. Their assessment focuses on the clarity of the project, the credibility of its assumptions and the quality of the supporting documents. The Finance HQ guide to building a strong application takes a similar approach, focusing on how the application is structured before even considering the amount requested.
An application that is easy for the system to process and convincing to a person needs a financing plan with a breakdown of costs, dated quotes and a cash flow forecast that includes a downside scenario. Banks tightening their terms for working capital financing expect precisely this demonstration of resilience.
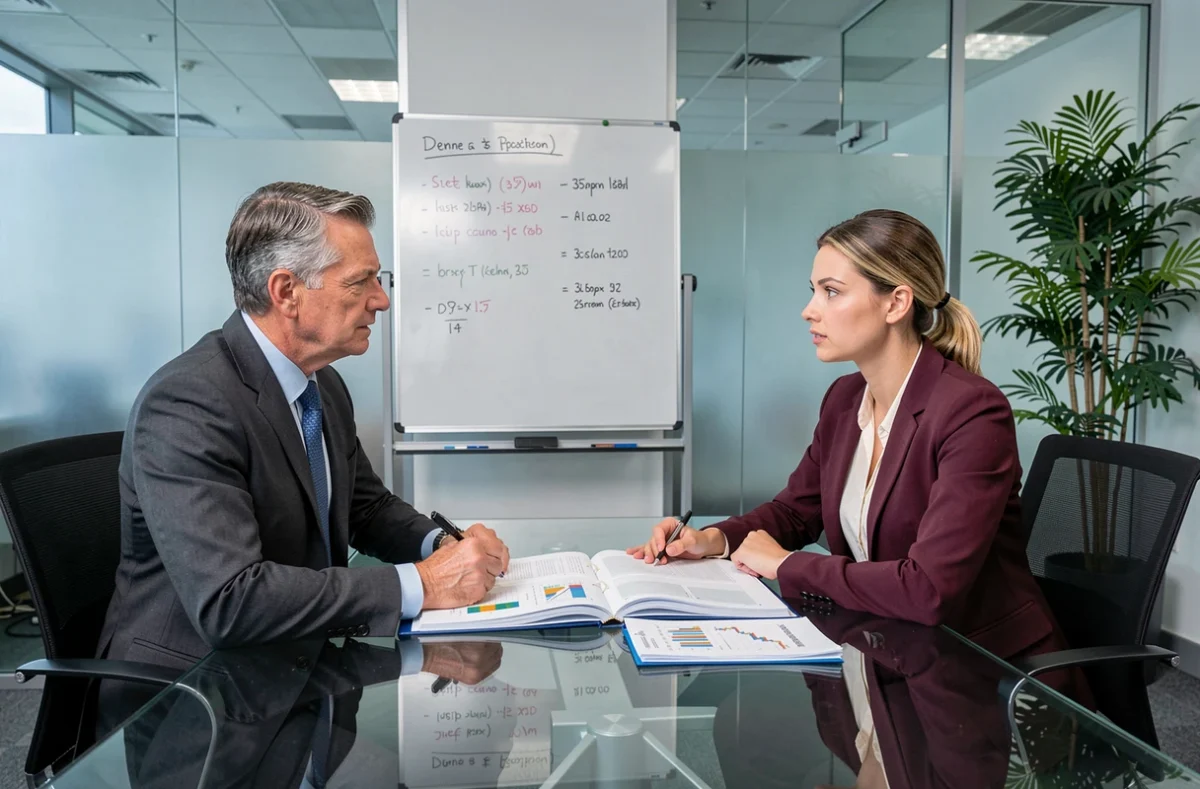
Financing plan and downside scenario: organizing the figures in your application
The financing plan is the central document. It sets out the funding requirements (investments, initial inventory, working capital requirements) alongside the sources of funding (personal contribution, bank loan, public grants). Every expense must be supported by a quote or written commitment.
Personal contribution and risk sharing
Your personal contribution demonstrates your commitment. Lenders see it as a sign of seriousness: applicants who invest their own funds share the risk with the bank. The amount expected varies depending on the type of project (start-up, business acquisition, real estate), but insufficient personal funding remains one of the most common reasons for rejection.
To supplement your contribution, a public guarantee can reduce the risk perceived by the bank. Bpifrance offers guarantees for financing start-ups and business acquisitions. Including this option in your application, along with the relevant program details, strengthens the credibility of your financing plan.
Month-by-month cash flow forecast
A projected income statement is not enough. Analysts want to see a monthly cash flow plan covering the term of the loan, or at least the first twelve to eighteen months. This document highlights cash flow shortfalls, timing gaps between receipts and payments, and your actual ability to repay.
Add a downside scenario with lower projected revenue. Showing how the business would cope with activity falling below expectations has become standard practice. The Banking & Finance 2026 guide to the French market confirms that higher-risk borrowers face tighter terms, making this stress test all the more useful.
Green investments and energy transition loans in your application
Financing tied to the energy transition is more than a cosmetic selling point. Funding from the European Investment Bank, made available through banks such as Crédit Agricole, targets energy efficiency, renewable energy and low-emission mobility projects.
For example, if your project includes purchasing energy-efficient equipment, insulating a premises or installing solar panels, list these investments separately in a dedicated line of your financing plan. Support them with quotes and technical specifications. Eligibility depends on the project and the bank’s approval, but presenting these costs separately increases your chances of accessing specific terms.
An application that lumps conventional and green investments together misses out on this opportunity. Separate them, document them and let the bank identify which costs could qualify for a dedicated financing facility.
Supporting documents and application mistakes that can hold things up
The quality of the documents you include affects how quickly your application is processed. An incomplete application goes to the bottom of the pile. Gather the following documents before any meeting:
- Valid ID, recent proof of address and, for an existing business, a Kbis extract issued within the last three months
- Your three most recent personal and business bank statements, latest tax assessments, and payslips or financial statements, depending on your status
- A complete business plan with market research, projected income statement, monthly cash flow plan and detailed financing plan with a breakdown of costs
- Dated quotes for every investment, a signed preliminary sale agreement or commercial lease, and, where applicable, a guarantee certificate from Bpifrance or another organization
The most common mistakes are not in the figures but in the presentation. A forecast without clearly stated assumptions, a financing plan where the personal contribution does not match the bank statements, or quotes that expired months ago: these inconsistencies prompt requests for additional information and can add several weeks to the review process.
When to submit your application
Submit your application once all the documents are ready, not simply because the project is urgent. Sending it too early with missing documents gives the impression that the project has been poorly planned. By contrast, submitting a complete application at the right time (before a lease deadline, after signing a preliminary sale agreement) shows that you have a firm grasp of the project timeline.
For a business acquisition, mandatory formalities involve fixed deadlines that determine when you can submit your application. Factor these constraints into the application process from the outset rather than discovering them during the review.
A strong financing application in 2026 is built not on outward optimism but on documented assumptions, clear risk sharing and up-to-date supporting documents. A carefully prepared application speaks louder than any presentation.